
Assessment of socio-economic benefits of the data centre sector in Portugal
Assessment of socio-economic benefits of the data centre sector in Portugal
WHAT ARE DATA CENTRES, AND WHY THEY MATTER
Data centres are at the heart of the digital economy, providing the infrastructure needed to store, process, and transmit vast amounts of data that underpin everyday digital services. They enable cloud computing, artificial intelligence (AI), e-commerce, streaming, and essential public services. As digital transformation accelerates worldwide, the role of data centres becomes even more central.
As AI development and adoption expands, so does the demand for computing capacity in AI-ready data centres. AI requires immense computing power for both development and deployment. From automating business processes and enhancing innovation to enabling new business models, AI is expected to deliver substantial productivity gains and economic growth across sectors. However, the development and deployment of AI solutions depend on robust digital infrastructure, especially high-performance, reliable data centres.
The global race to attract and build digital infrastructure is an important economic opportunity for countries that can offer the right conditions for data centre investment. Modern data centres designed to support AI workloads increasingly involve large-scale facilities and significant and expenditure, especially in construction-related activities.
KEY FINDINGS: THE SECTOR IS EXPECTED TO CONTRIBUTE SIGNIFICANTLY TO PORTUGUESE GDP AND EMPLOYMENT
We find that Portugal is well-positioned to become a key hub for data centres in Europe. The country’s strategic location, robust connectivity, competitive electricity prices, access to renewable energy and seawater and skilled workforce make it an attractive destination for data centre development.
The data centre sector can make very significant economic contributions to the GDP and employment in Portugal. Based on a macroeconomic model we find that between 2022 and 2024, the sector supported EUR 311 million in GDP and provided an average of 1,700 full-time jobs per year, including direct, indirect, and induced effects.
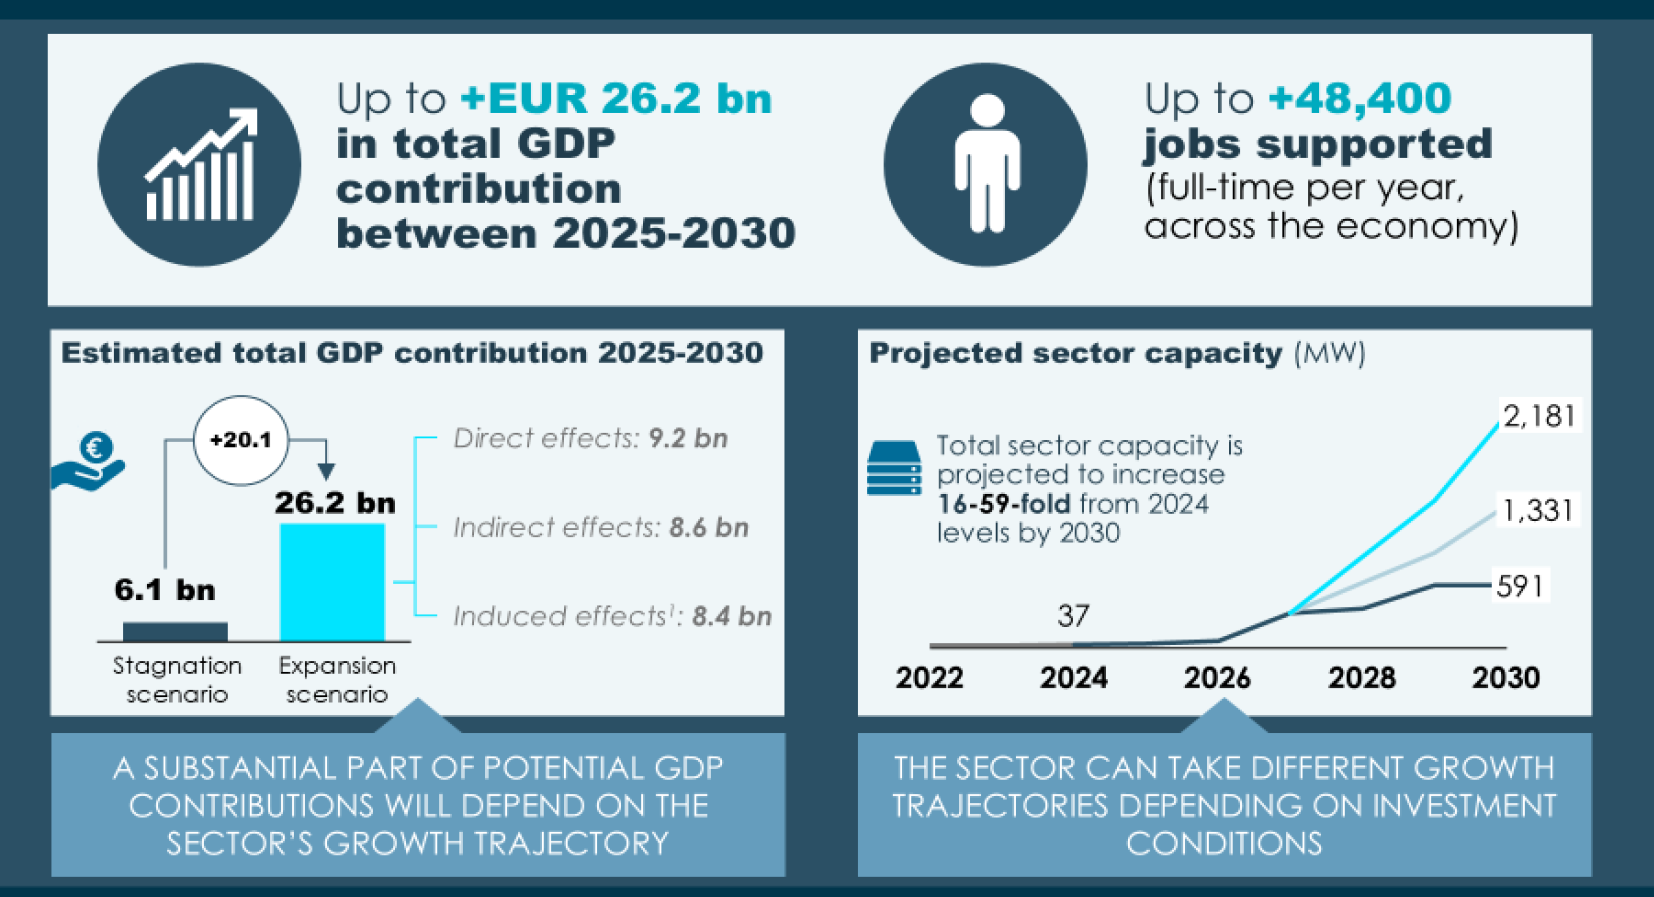
However, the sector's GDP contribution is expected to grow significantly until 2030, as a result of the expansion of the sector. We estimate that between 2025 and 2030 the sector will support between EUR 6.1 and 26.2 billion in GDP and an average number of jobs annually between 13,400 and 48,400, depending on the investment and policy conditions, considering direct, indirect and induced effects arising from data centres’ construction and operation.
Moreover, our research and interviews with a broad range of stakeholders suggests that data centres can support other economic and socioeconomic benefits, including (i) enabling digital transformation across the economy, (ii) supporting the development of tech clusters, (iii) attracting foreign direct investment, (iv) retain and attract skilled talent, and (v) foster regional development and social cohesion.
POLICY CONDITIONS WILL SHAPE FUTURE INVESTMENTS AND BENEFITS
The actual benefits, including supported GDP and employment, will depend on the growth trajectory of the sector, which will be influenced by investment conditions. To fully realise the sector’s potential, policymakers should focus on ensuring access to advanced technologies, streamlining permitting and regulatory processes, guaranteeing reliable electricity grid access, developing targeted incentives and zones for data centre investments, and promoting broader digital adoption across the economy.
The study was commissioned by Start Campus and is available in English and Portuguese.
In brief
Portugal's data centre sector could contribute up to EUR 26.2 billion to GDP between 2025 and 2030 and support 48,400 jobs a year, if investment conditions are favourable.
EUR 26.2 bn Potential contribution to Portuguese GDP from 2025 to 2030 under favourable investment conditions, equivalent to 1.3 per cent of GDP per citizen.
48,400 jobs Annual employment supported in the favourable scenario: 3,045 direct, 24,143 indirect, and 21,213 induced.
EUR 311 mn Contribution to GDP across 2022 to 2024, supporting 1,700 jobs a year.
30 per centHow far Portuguese electricity prices sit below the EU average, a material cost advantage where power is a leading expense.
25 per cent Estimated share of global subsea cables passing through Portugal, alongside fibre coverage reaching 92 per cent of premises, third highest in the EU.
Commissioned by Start Campus. Authors: Tuomas Haanperä, Neil Gallagher, Dr Bruno Basalisco, Dr Gerdis Marquardt, Rodrigo Cipriano, Manohar Gannavarapu, Okko Kivistö, Iraa Dahiya and Henrik Winkler. Published 15 April 2025. Historical data 2022 to 2024, projections to 2030. Portugal.
contact us
Click below to read more about our TMT & Digital service.
related Work
Google's hyperscale data centres and infrastructure ecosystem in Europe
Inside Denmark: Google’s European hyperscale data centres and infrastructure ecosystem
Inside Finland: Google’s European hyperscale data centres and infrastructure ecosystem
Inside Belgium: Google’s European hyperscale data centres and infrastructure ecosystem
Inside the Netherlands: Google’s European hyperscale data centres and infrastructure ecosystem
The economic impact of the forthcoming Equiano subsea cable in Portugal
About this analysis
Copenhagen Economics assessed how data centres fit into the digital economy and what the sector contributes to the Portuguese economy now and to 2030. The estimates come from an input-output macroeconomic model calibrated on Eurostat and OECD data, combined with desk research and interviews with stakeholders including AICEP, ANACOM, ANI, Altice Portugal, NOS, Equinix, CTS Group, Jacobs Solutions and CBRE. Three investment scenarios were modelled: stagnation, announced investments, and expansion.
The study measures the sector's contribution rather than its net impact, so it does not weigh benefits against potential drawbacks. Input-output models are static and assume no constraints on capital or labour, which makes them best suited to estimating the effects of a single sector. The model also excludes the wider spillover and enabling effects of data centres on innovation and productivity, which are discussed separately but not counted in the headline figures.